Recent changes to limited recourse borrowing arrangements (LRBAs) have introduced new restrictions on the types of property that self-managed super funds (SMSFs) can purchase using borrowed funds.
The changes have implications for SMSF trustees and advisers, as well as additional considerations for SMSF auditors. Here is a quick rundown of what’s changed and what you need to do.
What has changed?
From 10 August 2026, SMSFs can no longer enter into new LRBAs to purchase ordinary residential investment property.
Importantly, this does not mean SMSFs can no longer invest in residential property. They can still purchase residential property outright using existing fund assets, provided all other SMSF investment rules are met. The restriction applies specifically to new borrowing arrangements.
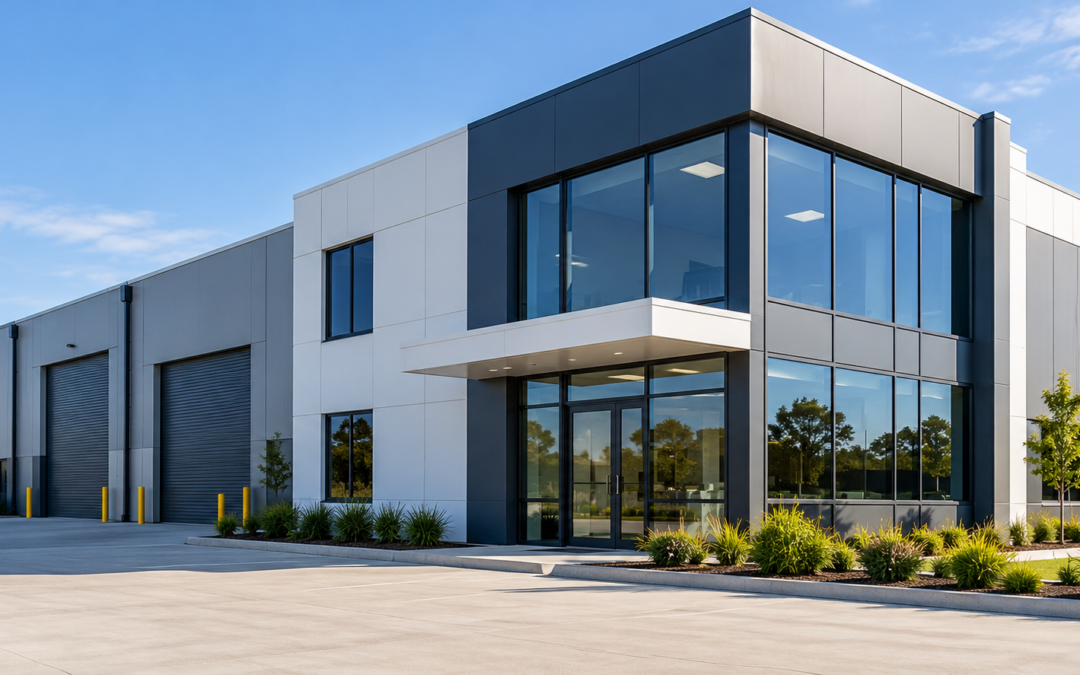
Under the new rules, property purchased through an LRBA must qualify as business real property. This generally means property used wholly and exclusively in carrying on a business, such as offices, warehouses, retail premises or commercial farms.
Importantly, the property’s actual use, rather than simply its zoning, determines whether it qualifies.
What about existing LRBAs?
Existing LRBAs entered into before 10 August 2026 can generally continue under the previous rules, including arrangements involving residential investment properties.
Refinancing may also be permitted, provided certain conditions are met. Transitional provisions apply to some arrangements entered into before the commencement date. However, trustees should seek advice before refinancing or restructuring an existing arrangement to ensure it remains compliant.
What will SMSF auditors be looking for?
As SMSF auditors, we’ll be paying particular attention to borrowing arrangements and property acquisitions to ensure they comply with the new requirements.
This includes:
- Commencement dates: Checking when an LRBA was entered into and whether the new rules apply.
- Property eligibility: Confirming that property acquired under a new LRBA qualifies as business real property. In future years, we will need an annual declaration to confirm the property continues to meet the definition of business real property.
- Ongoing compliance: Ensuring the property continues to meet the business real property requirements.
- Documentation: Reviewing loan agreements and supporting records, particularly where existing arrangements have been refinanced or restructured.
We’ll also continue to assess LRBAs against the broader SMSF compliance requirements, including the sole purpose test and related party transaction rules.
How can we help?
These changes highlight the importance of reviewing SMSF borrowing arrangements carefully, particularly when purchasing property or refinancing existing loans.
At Audit Your Superfund, we work closely with accountants and advisers to identify potential compliance issues and ensure SMSFs meet their audit obligations. If you have questions about the new LRBA rules or their implications for your SMSF clients, please contact our team.